When the rate is low, the real constraint shifts
A 3% mortgage doesn’t usually break a budget; the monthly payment does. When the rate is low, the trade isn’t “save interest” versus “be responsible.” It’s whether you want to convert flexible cash into home equity that’s harder to use without friction, fees, and time. The math can look clean on a spreadsheet, but real life adds delays and approvals.
The constraint tends to shift to optionality: keeping cash available for a job gap, a roof replacement, a medical deductible, or an investment chance that shows up at the wrong time. Extra principal payments reduce the loan balance, but they don’t reduce the required payment unless you refinance or recast, and those aren’t always cheap or even available when you need them.
So the question becomes: is today’s extra payment buying safety, or mostly buying illiquid comfort at the cost of flexibility?
Job volatility makes debt feel expensive anyway
That “illiquid comfort” starts to look different when income isn’t steady. A low rate doesn’t matter much if the paycheck can disappear for three months and the lender still wants the same payment on the first. In that moment, debt feels expensive because it’s not negotiable, and the penalty for being late is real: fees, credit damage, and stress that shows up fast.
People with variable comp, commissions, contract work, or a shaky industry often overestimate how usable their savings are under pressure. A severance timeline is uncertain, unemployment is smaller than expected, and the job search can run longer than the optimistic plan. If cash is tied up in equity, the “backup plan” becomes a refinance or HELOC application right when underwriting is least friendly.
So extra payments can be rational, but not for the rate. They’re a way to shrink the number of months you’re exposed to a fixed obligation when the next income shock is a matter of timing, not character.
Retirement timing can punish monthly payment obligations
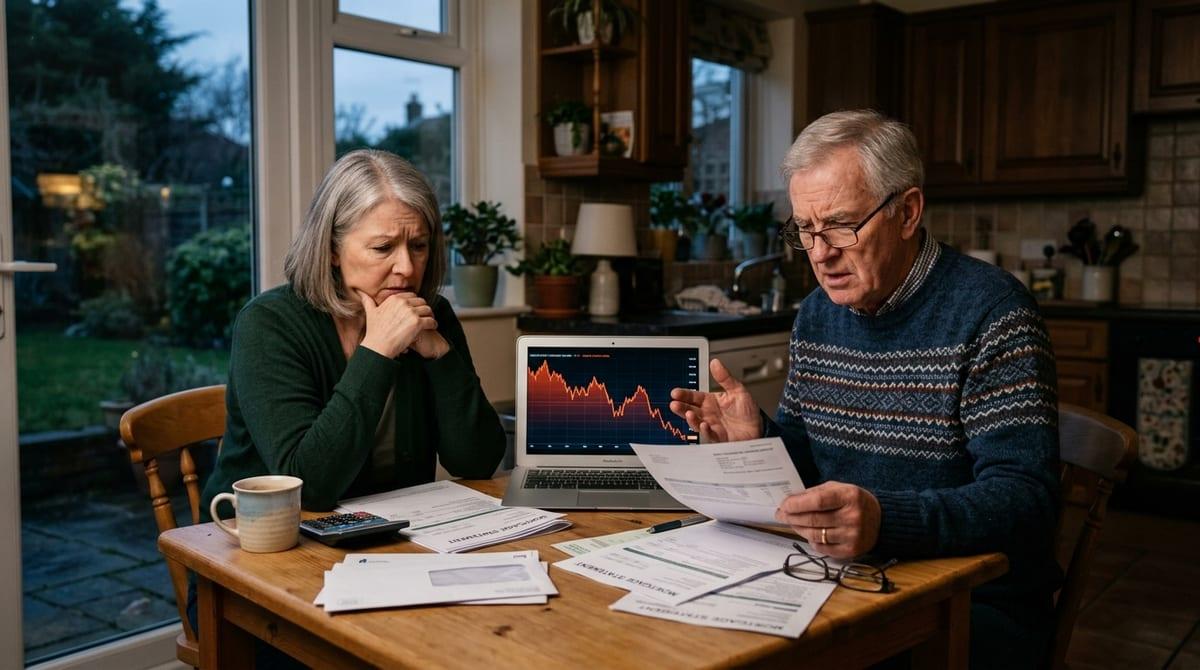
Retirement is where the “payment doesn’t change” detail stops being abstract. The mortgage might be cheap, but it still competes with a smaller paycheck, then a fixed draw from savings. If you retire a year earlier than planned, or a layoff turns into an unplanned bridge year, that monthly obligation can force bigger withdrawals at the worst time, even if the market is down.
It also messes with timing choices. Some people want to delay Social Security or keep taxable income low for health insurance subsidies, but a required mortgage payment can push cash needs up anyway. The mistake is assuming you’ll “just pay it from the portfolio” without noticing how it pins you to a minimum monthly burn rate.
In that setup, paying extra can be less about returns and more about buying a simpler retirement budget—especially if refinancing or a recast won’t be an option when income drops.
Psychological sleep value counts, but measure it
Even when the numbers favor keeping the loan, the “I hate owing money” feeling isn’t fake. The problem is that it’s easy to pay for relief twice: once with extra principal, and again when something expensive shows up and the only way back to cash is paperwork, waiting, and a higher rate. If the payoff plan is really about sleeping better, it needs a price tag, not just a vibe.
Try putting a monthly dollar value on the calm. Is it worth $200 a month? $600? Then compare it to what that same $200–$600 would buy elsewhere: an extra three months of cash reserves, disability insurance, or simply fewer worries about a job gap. Also watch for a tell: if the balance drops but the anxiety doesn’t, the payment wasn’t the source of the stress, and prepaying won’t fix it.
Relief that holds up during a bad month is the kind worth paying for.
The trap: paying extra, then needing cash later
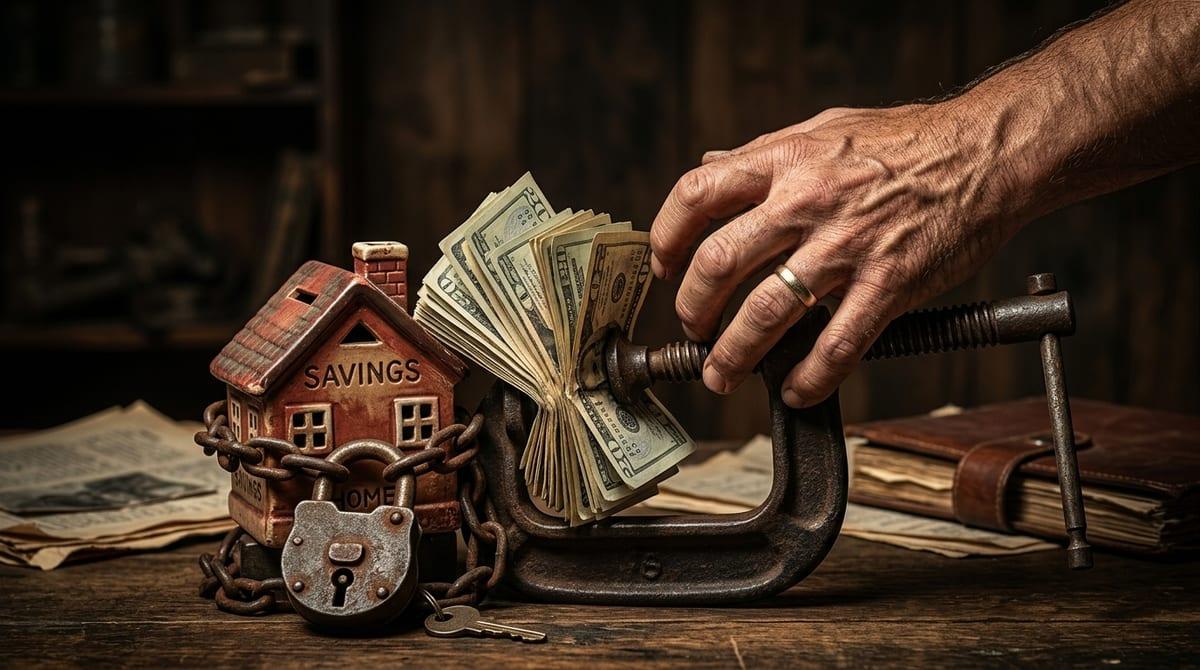
The pattern that bites people isn’t “I paid extra and regretted being debt-free.” It’s “I paid extra for two years, then needed $25,000 quickly.” The cash left the checking account on schedule, the loan balance looked better, and then a car replacement, a special assessment, or a job gap showed up on an inconvenient timeline. The mortgage didn’t care that the balance was lower; the required payment stayed the same.
Getting that money back is where the trap closes. A HELOC or cash-out refi takes time, comes with closing costs or fees, and the rate you get is whatever the market is that month—not the 3% you started with. Underwriting can tighten right when you’re applying because income is interrupted, credit utilization spiked, or the appraisal doesn’t come in where you assumed. The “emergency fund” becomes an application.
So the real risk isn’t losing return; it’s losing optionality at the exact moment timing matters.
Insurance, PMI, and cash reserves change the equation
Once optionality is the concern, a few “boring” line items start to matter more than the mortgage rate. If you’re still paying PMI, extra principal can be one of the few paydowns that acts like a guaranteed return, because it may remove a monthly charge. But the timing is messy: you might need an appraisal, you may have to hit a specific loan-to-value threshold, and some servicers won’t drop it the moment you expect.
Insurance can flip the priority, too. A higher homeowners deductible, rising premiums, or a new flood/wind requirement is a cash problem, not a rate problem. The same is true for disability or term life insurance: skipping coverage to send extra to principal can look “responsible” right up until the month you actually need the protection.
And if the cash reserve is thin, prepaying is basically choosing illiquidity on purpose. A real buffer—months of expenses plus the deductible—often buys more stability than a smaller balance does.
A workaround: partial payoff with a stop rule
That’s why a middle path often works better than an all-in payoff plan: treat prepayment like a risk-control move, not a moral goal. Pick a target that actually changes your position—dropping PMI, reaching a balance that makes a future recast worthwhile, or simply shaving enough years that retirement timing looks less fragile. Then stop.
The “stop rule” is what keeps it from turning into the same liquidity mistake with nicer intentions. Common rules are: never let cash reserves fall below a set floor (for example, 6–12 months of expenses plus insurance deductibles), pause extra principal anytime income becomes uncertain, and only prepay from surplus above that floor. If a big expense is likely within 12–24 months, cash wins by default because access speed matters.
This approach also forces an honest trade: if markets are down or a job search drags on, the rule prevents you from continuing to funnel money into equity while the only way back out is a HELOC at whatever rate exists that year.