You realize you’re short—what matters in the next 48 hours
You check your balance, do the math on what’s due, and it doesn’t fit. In the next 48 hours, the goal isn’t “fix the month.” It’s to stop avoidable damage: overdrafts, late fees, shutoffs, and a credit card swipe that pushes you into a worse spot.
Start with a quick snapshot: what cash is actually available (not “pending”), what payments will hit automatically, and what must be paid to keep basics running. If a bill can be late with a small fee, that’s different from rent, utilities, insurance, or anything that triggers an overdraft.
This part is uncomfortable because you may have to disappoint something—someone gets paid late. The win is choosing on purpose instead of letting timing choose for you.
What’s already spoken for (and what isn’t) when payday is still days away
Letting timing choose for you usually looks like autopay grabbing the last dollars in your account. Before you pay anything manually, list what’s already committed: rent, loan payments, subscriptions, transfers to savings, and any credit card or utility autopays. Check the exact pull dates in your bank and biller apps, because “due” and “withdraws” aren’t always the same day.
Then separate three buckets: money that must stay in checking to avoid an overdraft, payments you can pause or move without losing service, and “nice-to-have” charges that don’t need to happen this week. A gym membership and a streaming service are easy wins; turn them off today so they can’t sneak through tomorrow.
The annoying part: stopping autopay can take a few days, and some billers still try again. Leave a small buffer if you can, and make sure you know which payments you’ll replace with a manual payment later.
When everything can’t be paid, how do you choose what gets paid first?
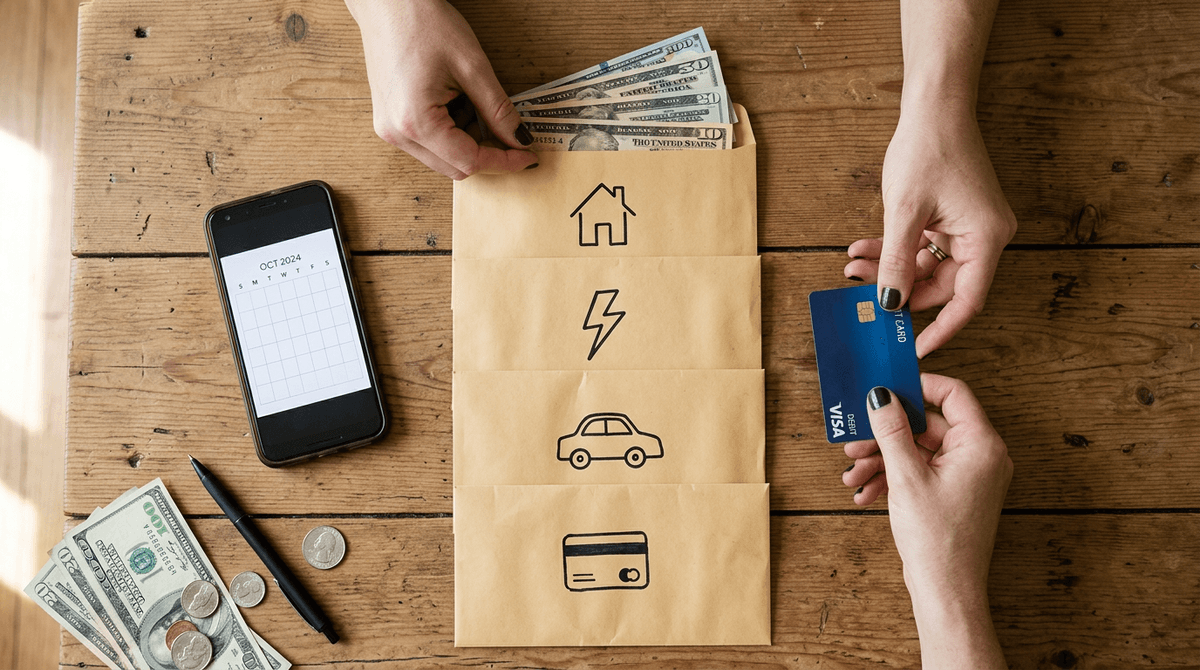
Replacing autopay with manual payments later means you now have to decide what “later” can safely be. When the money won’t cover everything, put bills into four lines on paper: keep-a-roof, keep-the-lights, keep-the-car/ability-to-work, and everything else. Rent or mortgage goes first because the downside is big and fast. Then utilities that can shut off, then insurance (especially auto), then minimums on anything that reports to credit.
After that, look for bills where the penalty is annoying but contained. A medical bill, a store card, or a small personal loan may charge a late fee, but they usually don’t create an immediate crisis the way a shutoff or a lapsed policy does. If you have two “important” bills competing, choose the one that triggers a chain reaction. Example: paying car insurance keeps you legal and avoids a cancellation that makes next month’s premium jump.
The real constraint is cash timing. A $35 overdraft or a returned-payment fee can erase the benefit of “trying to pay something.” If a partial payment won’t count, hold the money, make one clean payment you know will post, and line up the calls to push the rest out by a week.
Stopping the bleeding tonight: the fast cuts that don’t create new problems
Lining up those calls is easier when you’ve bought yourself a little room tonight. Start by freezing any spending that can trigger more fees: turn off card auto-updates in delivery apps, pause one-click buys, and pull the card out of your digital wallet so “just this once” doesn’t become three swipes. If you need food or gas, decide a hard number for the next 3–5 days and use debit or cash so you can’t accidentally stack interest and a higher balance.
Then cut what won’t create a new mess later. Skip extra principal payments, pause transfers to savings (temporarily), and hold off on paying any bill where a partial payment won’t count. Call your bank and ask to decline overdrafts on debit and ACH if that option exists; it’s better to have a card declined than to lose $35 you can’t spare.
The catch: some “cuts” cost you later—cancelling insurance or missing rent doesn’t save money, it creates a bigger bill. Once the leaks are plugged, you’re ready for the awkward ask: moving due dates and getting fees waived.
The awkward calls: asking for due-date moves and fee waivers without a script meltdown
That awkward ask usually happens when you’re staring at a due date you can’t hit, but you can hit it a few days after payday. Call before you miss it. Say you can pay on [date], ask for a one-time due-date change or payment extension, and confirm whether a late fee will still apply. If they offer a “promise to pay” note, take it, but write down the agent name, time, and any confirmation number.
Keep it simple: “I’m short this week. I can pay $___ on [date]. Can you waive the fee or move the due date?” Then stop talking. If they say no, ask what they can do: split payment, hardship plan, or a one-time courtesy waiver. Utilities and lenders often have options, but you may need to get to a supervisor.
Real-world downside: some companies can’t change anything once a payment is already late, and some “extensions” still report as late. If credit reporting is on the line, prioritize getting the minimum posted, then negotiate the rest.
Credit card damage control: minimums, interest, and when to stop using the card
Getting the minimum posted is often the cleanest way to keep one late payment from turning into a credit hit. If you can cover only one card, choose the one closest to 30 days past due, since many issuers don’t report a late payment to the bureaus until it’s at least 30 days late. If you can’t pay the full minimum, still call and ask for a temporary hardship plan or a fee waiver, but don’t assume a partial payment “counts” the way you want it to.
Interest is the quiet leak. If you’re carrying a balance, new purchases usually start accruing interest right away, and your payment often goes to older balances first. That’s why “I’ll put groceries on the card and catch up next check” can cost more than you expect.
So pick a line: stop using the card until you have a paydown plan. If you truly need it for gas to get to work, set a tiny cap and pay it as soon as payday hits, before it spreads.
Next month can be simpler: rebuilding a baseline budget that survives surprises
That “tiny cap” only works if next month starts with a plan that doesn’t assume a perfect week. On payday, write a baseline that covers rent, utilities, insurance, minimum debt payments, and groceries/gas first, then set one small “life” amount so you don’t rebound-spend because the budget feels like punishment.
Make it sturdier by building a buffer line on purpose: even $25–$50 per check into “unexpected” (meds, school email, car bulb) keeps the next surprise from going on the card. If cash is tight, treat that buffer like a bill and start smaller than you want; skipping it entirely is how you end up back in the same 48-hour scramble.
The practical constraint is timing. Bills don’t care when your paycheck lands. If due dates cluster, use your next calm week to move one or two dates, or split a large bill into two payments, so your checking balance doesn’t hit zero at the same point every month.